Where your deal stands
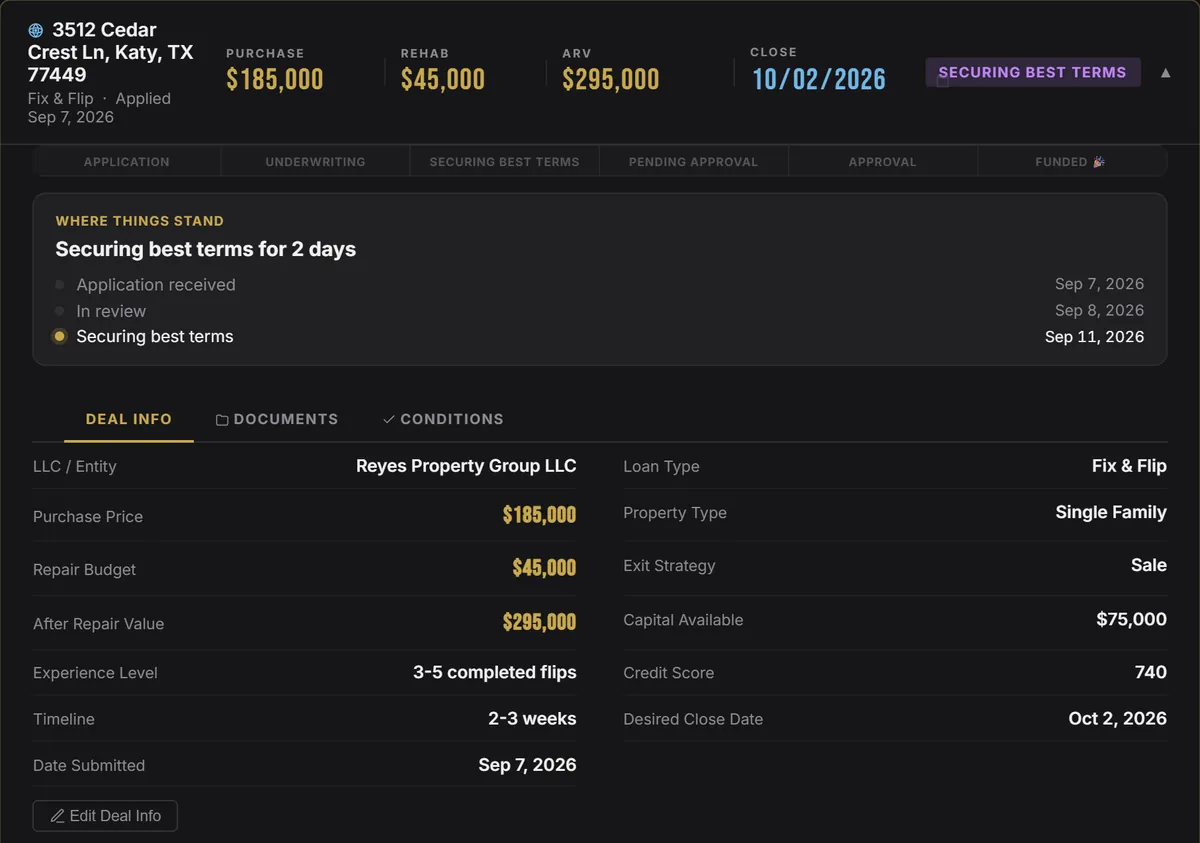
Your deal card shows the purchase, rehab and ARV, the stage you're in and every step so far, from application received to funded.
Live statusTimeline
Hard money, DSCR and new construction loans
Enter your deal to see the estimated loan amount, fees and cash to close. When you're ready, apply and we'll compare options from the lenders in our 400+ lender network that fit your deal.
Prefer to talk it through? Call or text Micah at (281) 636-5682.
 Mini Term Sheet
Capital Kings LLC
Live
An estimate, priced on our Texas programs. Your final terms depend on the property, your credit and experience, and the lender's review.
Loan programs
Compare starting rates and requirements below. Each program page explains the pricing and includes a worked example and calculator.
The loan covers the purchase and the rehab. The rehab money comes out in draws as the work gets done, and there are no tax returns to hand over.
Texas 5% down program. Loan capped at 75% of ARV.
Swipe for more programs
Buy or refinance a rental and qualify on what it rents for instead of your income. No tax returns or W-2s.
Lot and build in one loan, with the build funded in draws. Up to 95% of cost with a financed interest reserve (680+ credit).
0% down when purchase plus rehab fits under 70% of ARV. You still bring closing costs.
Just the purchase, no rehab money and no draws. Built for auction buys, off-market deals and houses that don't need work.
Pull equity out of a property you own and put it to work on the next one. A short-term bridge refi and a 30-year DSCR refi solve different problems, and we'll tell you which one fits.
Cash, cost and speed pull against each other. Here is how they usually line up.
Keep more cash available for the rehab and your next deal.
Best when minimizing borrowing cost matters more than keeping cash in your pocket.
Best when timing matters more than minimizing total borrowing cost.
Usually a higher rate, a higher origination fee, or both.
Lower rates usually require more cash up front.
Your documents need to be ready on day one.
You usually can't optimize all three at once. Tell us what matters most and we'll structure the deal around it.
Pick the one that matters most and we'll carry it into your application.
Your estimate
When we give you numbers, this is what you're looking at. Pick a line to find it on a sample term sheet.

The loan
At closing
Each month
Point at any line to see where it sits on the sheet and what it means.
The borrower portal
Once you apply, your term sheet, documents, e-signatures and closing conditions live under one login, on your phone or your laptop.
Swipe through the portal
Your deal card shows the purchase, rehab and ARV, the stage you're in and every step so far, from application received to funded.
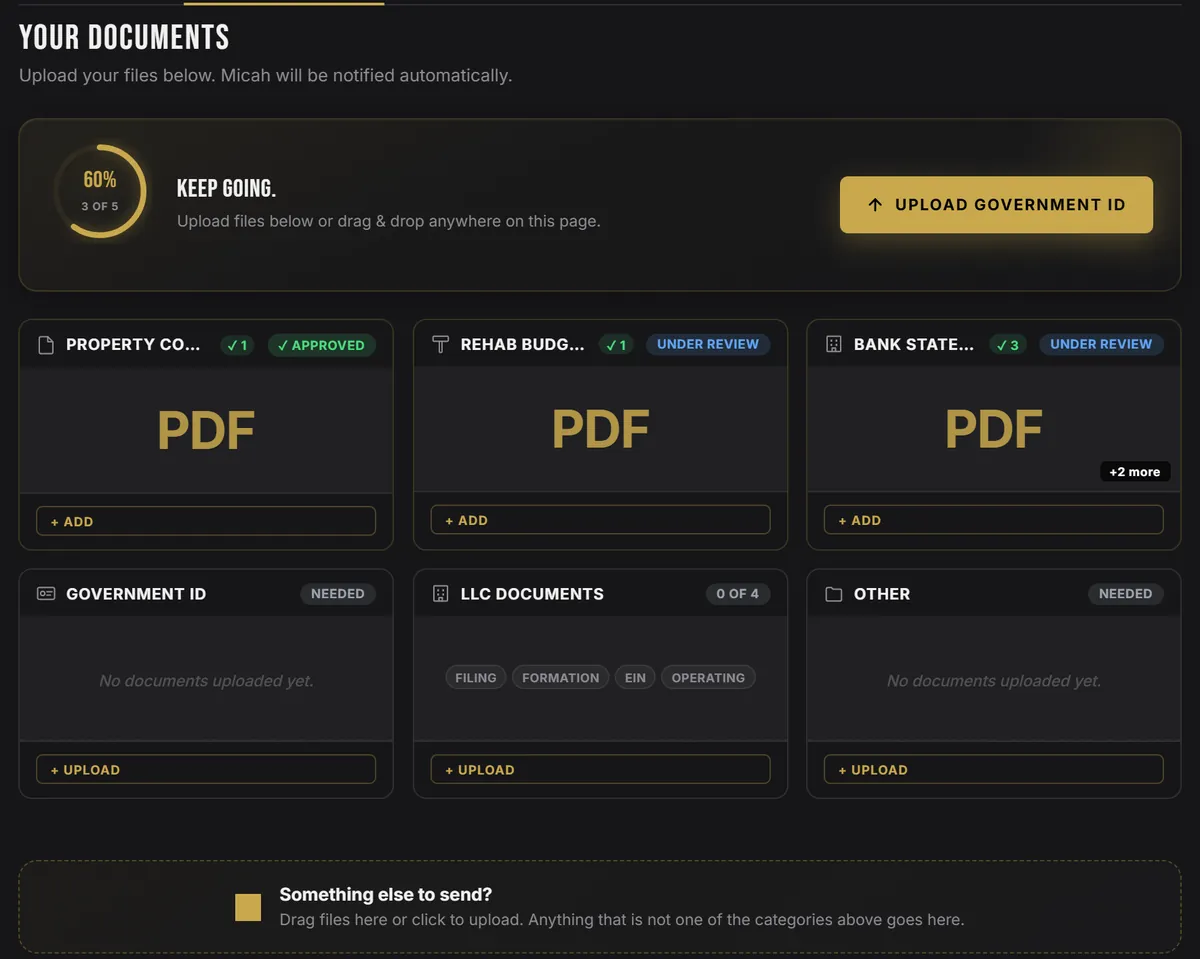
Upload from your phone or your laptop. Each category shows whether it's still needed, under review or approved, so you always know what's left.
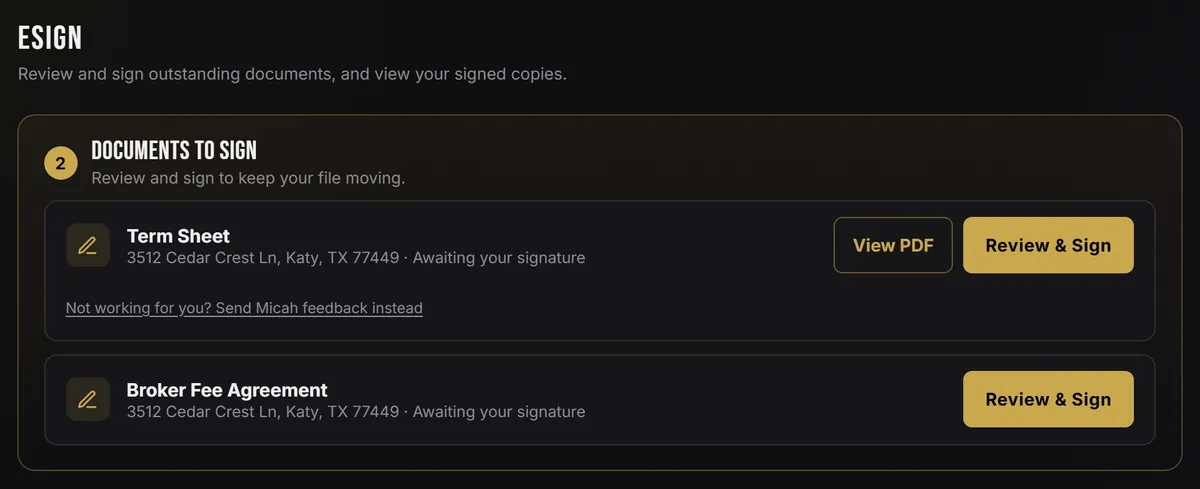
Review and sign your term sheet and broker fee agreement right in the portal. There's nothing to print or scan.
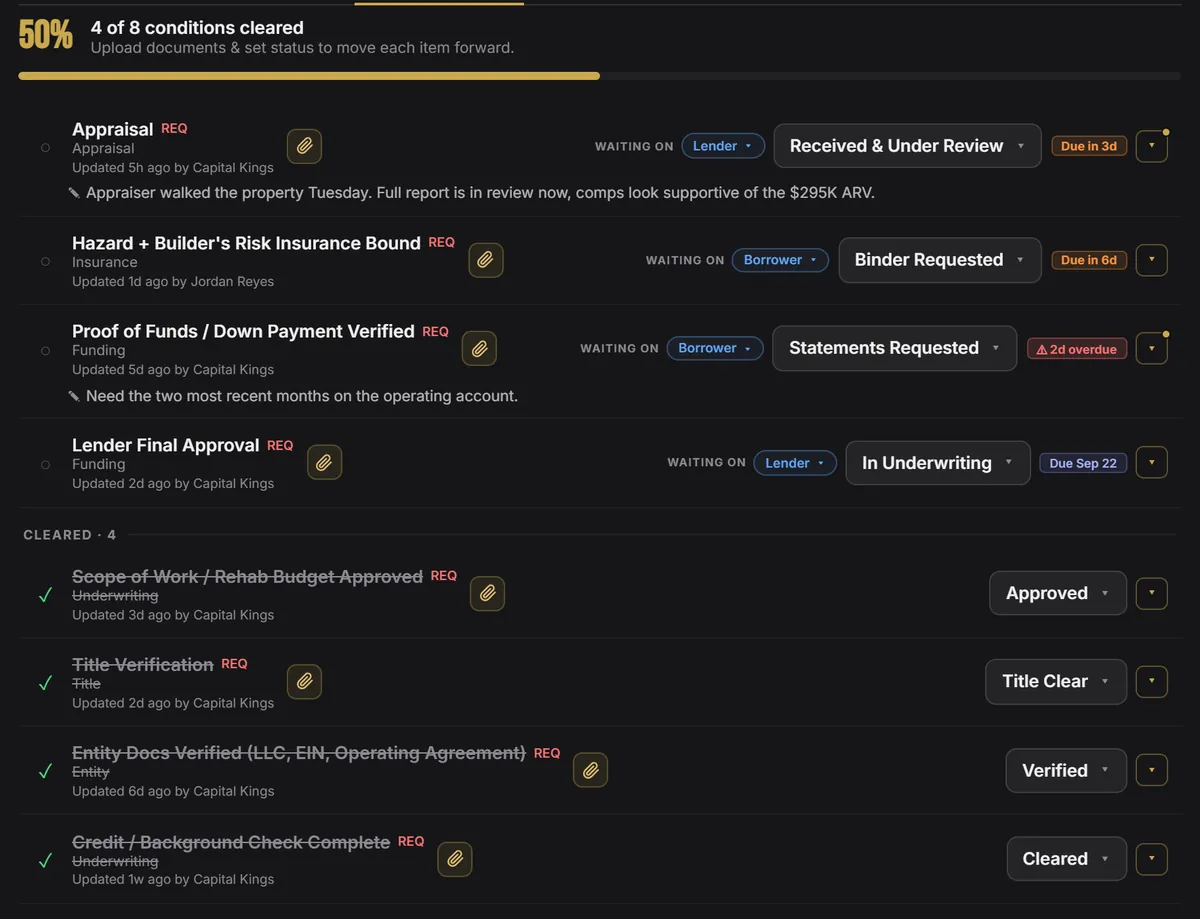
Each closing condition shows who it's waiting on and when it's due, from the appraisal all the way to the lender's final approval.
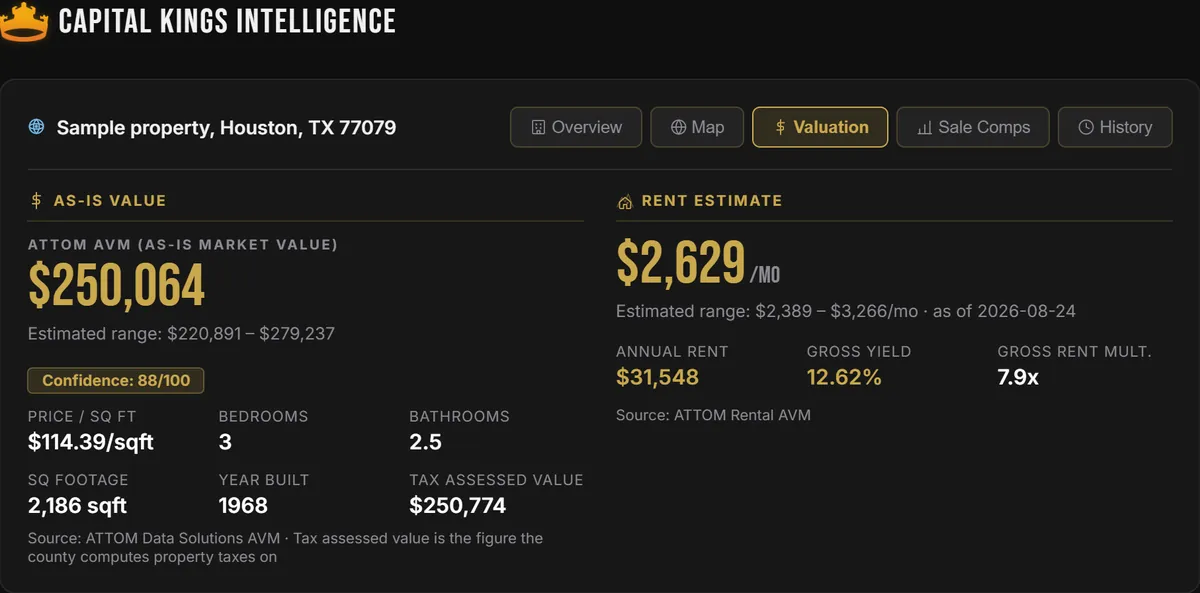
See an estimated property value, estimated rent, comparable sales and sale history inside your deal. These help us discuss the property's value and financing; they don't replace a lender's appraisal.
Lending coverage
Select a state to see the loan programs and terms available there.
Tap a gold state to see its local loan programs

A letter from the founder
When you're running a flip, you shouldn't have to guess what your loan costs. My job is to shop it, explain every line in plain English and help get it closed.
I'm the kind of person who asks a million questions before I'm comfortable with something, so ask me anything. If a fee doesn't make sense, or you're not sure how much cash you'll need or what happens if the project runs long, let's work through it before you commit to the loan.
From application to funded
See the whole process, step by stepTell us about the property, the numbers and your experience. No account needed to start.
A preliminary term sheet downloads the moment you submit: loan amount, rate, fees and cash to close.
Making offers? Send two months of bank statements and your letter usually comes back the same day.
We place it with the lender that fits best, or show you the top options side by side when more than one fits.
Sign your term sheet, upload documents and watch each condition clear.
Most fix and flip files fund in 5-14 days once the file is complete. As little as 72 hours on the fastest programs in select states.
For realtors & wholesalers
Referral program · what you earn
Your referred borrowers
Sample referrals, the way your partner portal tracks them.
Why a broker
We match your deal with the lenders that fit based on the property, your experience, credit, cash available and timeline. When there are multiple strong options, we compare them side by side. When one lender is clearly the best fit, we'll tell you why.
That doesn't mean we send every deal to every lender. We narrow the field first, then shop it where doing so can actually improve your terms.
From the blog
Swipe for more articles
 Hard MoneyHow to Get an Instant Hard Money Term SheetBuild a real, itemized fix and flip term sheet in about 3 minutes. No phone call, no credit pull. See your loan amount, rate, fees, and cash to close before you call a lender.
 Hard Money 101Hard Money Loan Requirements in Texas: What You Need to Qualify in 2026What Texas hard money lenders actually require in 2026: credit by band, experience tiers, down payment by program, cash to close and reserves, the document list, the LLC rule, property and location rules, and the 5-14 day timeline to fund.
 StrategyCash to Close: The Number Most Borrowers Miss Until It's Too LateDown payment is just the start. Here's everything that goes into your actual cash-to-close figure on an investment property loan.
 Fix & FlipFix and Flip Closing Checklist for Hard Money LoansThe documents a hard money loan needs, the 11 conditions a fix and flip file clears, which four are yours, and what cash to close really includes.
 Hard MoneyHard Money Loans With No Money Down: What 100% Financing Really Means100% financing on a fix and flip funds the purchase and the rehab, but it is capped at 70% of ARV and priced higher. What it costs, what still wires at closing, and the 5% down option most investors should take instead.
 Hard Money 101How Construction Draws Actually Work on a Fix & Flip Loan (The Rehab Holdback Explained)Your rehab budget is not funded at closing. Here is how construction draws and the rehab holdback really work on a hard money loan, and how to read your HUD.
 Fix & FlipPurchase-Only Hard Money Loans vs Fix & Flip Loans: Which One Do You Actually Need?Purchase-only hard money vs a fix and flip loan: real Houston numbers, the cash-at-closing trade most lenders skip, and how to pick in 60 seconds.
 PartnersThe Infinite $500 Referral Fee: Get Paid Every Time Your Investor ClosesYou send us a borrower. Every loan they ever close with Capital Kings pays you a $500 referral fee. Here is how the program works.
 Hard MoneyDirect Hard Money Lender vs. Broker: The Honest BreakdownThe questions to ask a direct lender, what a broker really costs you, and how investors raise private money as they grow.
 Hard MoneyDutch Interest vs. Standard Interest on Hard Money LoansUnderstanding the difference between dutch interest and standard interest structures, and when each one works in your favor.
 Hard MoneyPoints, Fees & Rate: How to Actually Compare Hard Money LendersMost investors compare lenders on rate alone. Here's how to add up the origination, fees and rate so you know what a loan really costs.
 StrategyThe 70% Rule: A Good Starting Point, Not the Whole StoryThe 70% rule is the fastest way to screen a flip, but it is not how you should actually decide. Here is what it really tells you and where it falls short.
 Non-QMWhat Is a Non-QM Loan and Why Do Investors Use Them?A plain-English breakdown of non-QM lending: who it's for, how it's underwritten, and why so many real estate investors use them.
We're a broker. Instead of pushing one lender's loan, we send your deal to the lenders in our 400+ lender network that fit it and bring back the best structure for what you care about most, whether that's the least cash to close, the lowest rate or the fastest close.
Most fix and flip files fund in 5-14 days once the file is complete, and we've closed in as little as five days. On the fastest programs in select states it can be as little as 72 hours, with your documents ready on day one. DSCR rental loans and new construction take longer, usually 21-30 days.
No. It's a starting point based on what you enter. A lender still reviews you, the property and your documents before anything is approved, and your term sheet says so at the top.
The property address, the purchase price (or your current loan balance on a refinance), your rehab or construction budget if there is one, what you plan to do with the property, and the closing date you're working toward.
No. The application takes about 3 minutes and there's no credit pull. You tell us your credit range up front, and the lender pulls credit later, during underwriting.
It depends on the program and the deal, and your term sheet shows your down payment, every fee and your total cash to close before you sign anything. The lowest is 0% down (100% financing) when purchase plus rehab fits under 70% of ARV. In the major Texas metros that takes 650+ credit, even on a first flip. Outside Texas it takes 2+ completed flips. Either way, you still bring closing costs.
No. Fix and flip and bridge lenders look at the deal, your credit, your experience and the cash you have available. DSCR rental loans qualify on the property's rent, so there are no tax returns or W-2s to hand over.
Yes. In the major Texas metros, our 5% down program takes first-time flippers with 590+ credit, and the lender funds 100% of the rehab through draws. One of our Texas lenders also works with first-time investors and doesn't set a minimum credit score. That helps most when a lower score comes from high credit card balances. It doesn't help with a bankruptcy or foreclosure, which lenders generally won't close on. Outside Texas, a first flip usually starts at 10% down with 680+ credit, and the lower down payment programs open up as you complete deals.
Our broker fee is 1% of the loan with a $2,000 minimum, and it's the only money we make on your loan. It's disclosed before you sign, next to every lender and third-party fee, so you can see exactly who gets paid what.
We place investor loans in 37 states, with our deepest roots in Texas. Every state we lend in has its own page with programs, pricing and local markets, and you can see all of them on our states page.
No. We only arrange business-purpose loans on investment property: flips, rentals, new construction and bridge loans. We don't do loans on a home you live in.
Enter the property details to get your preliminary term sheet, or call Micah to talk through the deal first.
